We are a digital agency helping businesses develop immersive, engaging, and user-focused web, app, and software solutions.
2310 Mira Vista Ave
Montrose, CA 91020
2500+ reviews based on client feedback
What's Included?
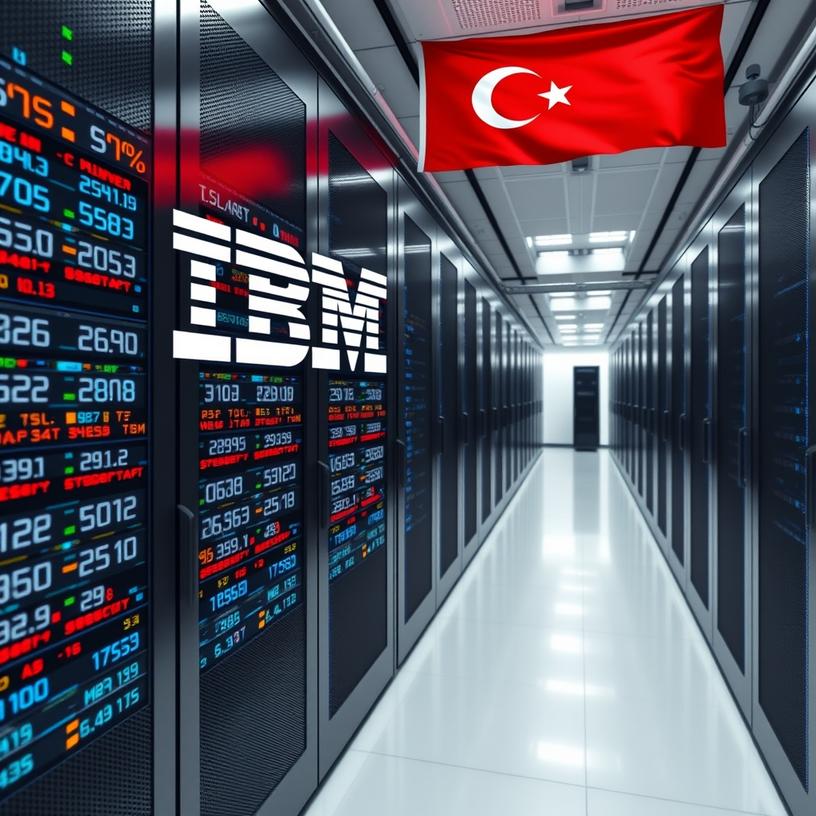
ToggleWhen IBM announced a fresh partnership with Turkey’s Kredi Kayıt Bürosu, the headlines focused on the size of the data flow. The bureau handles credit information for individuals and businesses across the country, and the new contract asks IBM to keep the system running smoothly for roughly 23 million records every single day. That number sounds huge, but it is only the tip of the iceberg when you think about the speed and reliability required. In plain terms, the AI platform must read, score, and store each entry in a matter of seconds, or the whole credit‑reporting chain could stall. The deal is a clear sign that big‑tech vendors are willing to go deep into local markets, even when the technical bar is set very high.
IBM’s appeal lies in its mix of cloud services, classic mainframe strength, and AI tools that can learn from patterns in data. For a company that has been around for more than a century, the shift toward hybrid‑cloud and AI has been a survival move. The firm now offers a stack that can sit on‑premises, in a public cloud, or in a blend of both, which fits the Turkish regulator’s demand for data sovereignty. By adding AI models that can flag risky credit behavior, the bureau hopes to cut down on manual reviews and speed up loan approvals. The partnership also gives IBM a foothold in a market that is still catching up with Western AI adoption rates.
The real eye‑opener is the volume: 23 million transactions a day translates to more than 800 million records a month. Each record may contain personal identifiers, payment histories, and dozens of numeric fields. Processing that amount of data in real time means the underlying infrastructure has to be both fast and fault‑tolerant. A single glitch could delay thousands of loan applications, affect credit scores, and erode trust in the system. The bureau’s existing legacy platforms were not built for this kind of load, which is why IBM’s modern stack is being called in.
From a technical standpoint, the biggest challenges are latency, scalability, and security. The AI models need fresh data every few minutes, so the pipeline can’t afford long batch windows. To meet that demand, IBM will likely use a combination of in‑memory processing and distributed computing across several data centers. At the same time, the solution must obey strict Turkish data‑protection laws, meaning that most of the computation has to stay inside the country’s borders. Encryption, access‑control logs, and real‑time monitoring become non‑negotiable parts of the architecture.
What does this mean for the broader market? First, it shows that large‑scale AI projects are moving beyond the usual suspects in finance, like banks and insurance firms, into credit bureaus that sit at the heart of everyday borrowing. Second, it puts pressure on other vendors to prove they can handle similar loads without breaking the bank. Finally, it may encourage Turkish businesses to trust AI‑driven decisions more, because the technology will be backed by a global name and a transparent audit trail. The downside is the risk of over‑reliance on algorithms that may inherit bias from historic data, a problem that IBM will have to address openly.
In the end, the IBM‑Kredi Kayıt partnership is a test case for how AI can be woven into the fabric of a national credit system. If the platform can keep up with the daily flood of 23 million transactions while staying secure and compliant, it will set a benchmark for similar projects worldwide. Success could open doors for more AI‑driven services in Turkey, from fraud detection to personalized financial advice. Failure, on the other hand, would remind us that speed alone does not guarantee value. Either way, the next few months will be a learning period for both IBM and the Turkish credit bureau, and the results will be watched closely by anyone interested in the future of AI in finance.
Source: Original Article
Comments are closed